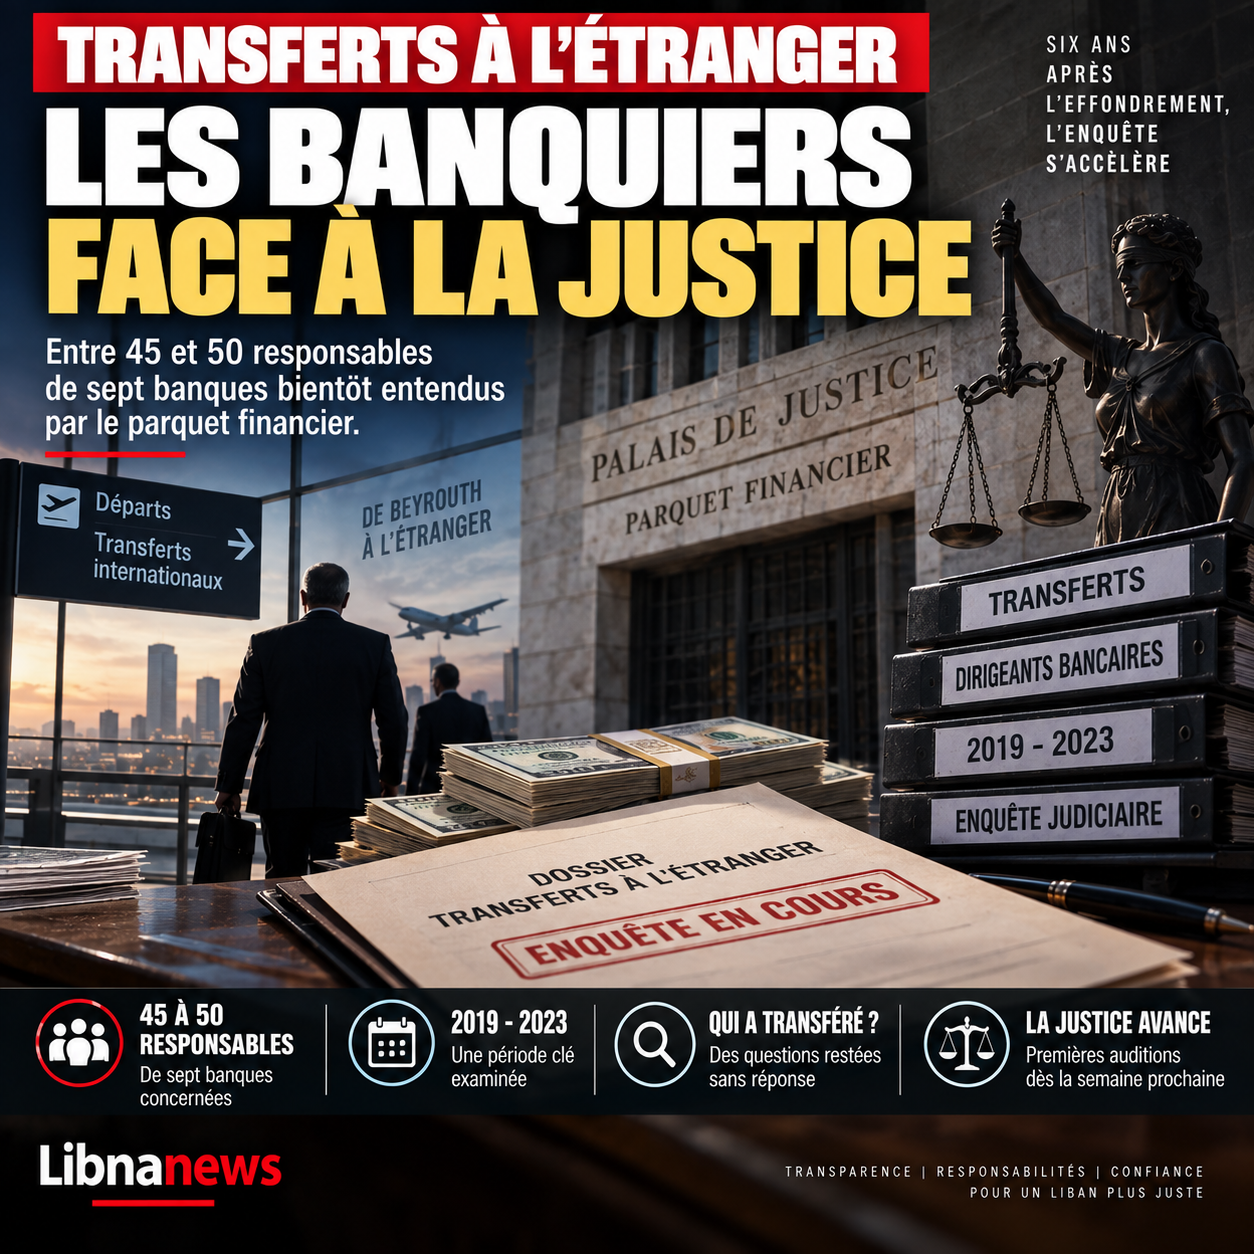
Six years after the Lebanese banking collapse, the case of remittances abroad is finally entering a concrete judicial phase. The financial attorney general, Judge Maher Cheaïto, is due to begin hearing from bank officials next week. A first set of data transmitted by the Bank of Lebanon covers between 45 and 50 directors and senior managers of seven institutions. The transactions examined cover a particularly sensitive period from 1 July 2019 to 1 December 2023. They ask a question that has remained largely unanswered since the beginning of the crisis: who was able to transfer his money out of Lebanon while the majority of depositors were progressively prohibited from freely disposing of his dollars?
The dossier is no longer limited to global estimates, lists mentioned in the press or suspicions accumulated since October 2019. Banking data is now in the hands of the financial prosecutor. According to information available on Thursday, 17 September, the Bank of Lebanon (BDL) transmitted last week to Judge Maher Cheaito a first set of information concerning 45-50 board members and senior officials of seven Lebanese banks. The names of the persons and establishments concerned have not been made public. Other datasets need to follow, meaning that the current scope is only a first step in the investigation.
The stakes are considerable for applicants. Starting in autumn 2019, banks imposed drastic restrictions on dollar withdrawals and international transfers on their own initiative. However, Lebanon had not adopted a general capital control law that uniformly regulated such restrictions. The court must now determine whether, during that period, directors, officers, major shareholders or clients enjoying privileged relationships could transfer funds abroad under conditions different from those imposed on the rest of the depositors.
45-50 bankers in a first list
The number is now at the centre of the file: between45 and 50 directors and senior officers, owned byseven banksthe first set of information provided to the financial prosecution. These people are not charged. Their presence in the data transmitted to the court means that their operations must be examined and that some of them must be heard.
This legal distinction is essential. A transfer of funds to foreign countries was not in itself a criminal offence in Lebanon. The country had not adopted a comprehensive legal control of capital when the crisis broke out. The investigation must therefore go much further than the mere finding of a transfer. It must establish the date of the transaction, its amount, its actual beneficiary, the nature of the funds, the conditions under which the bank authorised it and, above all, whether the beneficiary had a treatment to which other depositors no longer had access.
The Public Prosecutor’s Office will also have to determine whether certain transactions may be subject to other legal qualifications. The possible existence of privileged information, an abuse of function, a suspicious transaction or preferential treatment must be established individually. Justice must therefore distinguish between ordinary and lawful transfers and transactions that may have benefited from special circumstances.
The names of the 45 to 50 people affected by this first wave were not officially disclosed. It would therefore be premature to assign invitations to specific leaders or to draw up a list of allegedly targeted banks. The confirmed information at this stage covers their number, their functions and the number of establishments concerned.
Judge Maher Cheaïto at the centre of the case
The change is largely due to the arrival of the case before financial attorney general Maher Cheaïto. As early as September, it was announced that a first set of data prepared by the Bank of Lebanon would be transmitted to the prosecutor ‘ s office in order to initiate hearings and, when the evidence so warrants, to judicial proceedings.
This transmission has now begun. It gives the prosecutor the opportunity to work on individualized operations rather than on the only global evaluations that have been circulating for six years. The hearings expected next week are thus an important step, but not yet a judgement on responsibilities. The prosecutor will have to compare the persons heard with the bank data, gather their explanations and then decide on appropriate legal action.
Maher Cheaïto had already placed transfers abroad among the priority files of the financial prosecution. By August 2025, he had taken a decision targeting natural and legal persons, including bankers, who had transferred funds outside the country during the crisis. He requested the repossession in Lebanese banks of amounts equivalent to the sums concerned, in the same currency and under the supervision of the financial prosecutor.
The scope of that decision had generated legal debate, in particular because the international transfer of capital had not been prohibited by general law. However, it had marked a break: the issue of cash outflows was no longer considered merely a political or moral problem, but a set of transactions that could be examined individually by the courts.
Transfers abroad: why July 2019 counts
The period under review is one of the most important aspects of the investigation. The information provided to the Public Prosecutor’s Office covers transactions between the1 july 2019 and 1 december 2023. The departure date therefore precedes by more than three months the uprising of 17 October 2019 and the bank closures that accompanied the visible beginning of the crisis.
This choice makes it possible to examine the movements of capital in the last few months preceding the collapse. In the summer of 2019, financial tensions were already high. Foreign currency inflows needed to operate the system were decreasing and difficulties in accessing the dollar were gradually becoming visible. After 17 October, the situation changed: banks closed for several weeks before reopening by limiting withdrawals and, above all, transfers to abroad.
Examination of the period prior to 17 October can therefore be used to determine whether certain actors have moved substantial sums before access to currencies is virtually closed to ordinary depositors. This does not in itself demonstrate the existence of an offence or privileged information. The timeline simply allows investigators to compare transactions with the gradual deterioration of the financial situation.
This question had also been identified very early. Circular No. 154 of the Bank of Lebanon, issued on27 august 2020, went even further. It concerned customers who transferred more than$500,000from abroad1 july 2017and asked banks to encourage them to bring back some of these funds.
The precedent of Circular 154
Circular 154 now provides an essential element in understanding why bank managers’ transfers occupy a special place. For ordinary customers who have transferred more than $500,000 since July 2017, the BDL asked banks to encourage them to reposition the equivalent of15 %amounts transferred to a special account for five years.
The rate rose to30 %for several categories directly related to banking power: bank presidents, board members, major shareholders and senior executives. The same rate was for politically exposed persons. As early as August 2020, the Bank of Lebanon itself recognized the need to specifically identify transfers by persons controlling or managing the institutions.
However, this circular was not a general obligation to return capital. It asked the banks to encourage the persons concerned to repatriate part of the funds, in particular in order to restore their liquidity to their foreign correspondents. It therefore did not amount to a judicial conviction of persons who transferred money.
His interest is now documentary. Banks have necessarily had to examine some of the transfers that correspond to the BDL criteria. Six years later, the question becomes what these data provide and to what extent they can be used by the judicial authorities.
The core of the case: inequality between applicants
This is where the real issue is. At the end of 2019, commercial banks introduced de facto capital controls. Regular customers have gradually lost the opportunity to transfer their former dollar deposits abroad. The withdrawals were also capped, followed by mechanisms that resulted in significant losses to depositors when bank dollars were converted into pounds at lower market rates.
However, these restrictions were not originally based on a capital control law passed by Parliament. Each bank applied its own rules. In particular, institutions could authorize certain transfers considered urgent, for example for medical or university expenses, while general access to international transfers was blocked.
This situation has created a major legal and political issue. If influential officers, directors, shareholders or customers were able to move their capital while the same banks refused transfers to their other depositors, on what criteria were these decisions taken? It is less the existence of the transfer than the conditions under which it has been authorized that become decisive.
The Cheaito investigation is intended to move from this general question to the examination of specific files.
2.276 billion dollars to Switzerland in a few weeks
The first investigations launched after the collapse had already revealed the importance of capital outflows. An investigation by the Banking Control Board estimated that$2.276 billiondeposits transferred from Lebanese banks to Switzerland betweenoctober 17 and december 31, 2019.
This figure represented only a fraction of capital movements. It concerned Switzerland and a period of a few weeks, not all international transfers made before and after the start of the crisis. A broader survey had also covered transfers to different countries from 1 July 2019, but its full results had not been made public.
At the time, the Lebanese authorities had requested assistance from Switzerland after reports of significant transfers by politically related persons. The process did not succeed as expected. The Swiss authorities had considered that the Lebanese request should include more precise information on the facts, persons and offences suspected.
Bank secrecy was then one of the obstacles to obtaining and transmitting detailed information. This situation explains in part why, despite the scale of the crisis, the transfer case remained for years without leading to a large individualised judicial procedure.
The bank secrecy lock has been largely lifted
The legal framework has since changed dramatically. Parliament had begun to change the banking secrecy regime in 2022. A new step was taken on the24 april 2025with the adoption of Act No. 1/2025, promulgated by President Joseph Aoun.
This reform allows the Bank of Lebanon, the Bank Control Commission and the National Deposit Guarantee Corporation to obtain information previously covered by bank secrecy in the performance of their supervisory tasks. Above all, the scheme has a retroactive scope of ten years, which covers the entire period of the 2019 crisis.
This change is crucial for the case currently transmitted to Maher Cheaïto. In the early years of the crisis, access to bank data had been regularly invoked as an obstacle to investigations. The current framework provides the supervisory authorities with a much broader capacity to review accounts and transactions.
The question is therefore no longer just whether lists exist. It is now a question of determining what they contain and what judicial follow-up can be given to the transactions they document.
Documented transfers during deposit blocking
Several surveys have already shown that funds have continued to leave Lebanon while access to deposits is becoming extremely difficult. An international investigation based on disclosed bank documents had, inter alia, established thatNady Salamé, son of the former Governor of the Bank of Lebanon Riad Salamé, had transferred more$6.5 millionabroad during the crisis.
This case does not, of course, make it possible to conclude that the operations currently examined by the prosecution have the same characteristics. However, it illustrates why the issue of transfers has become central: bank restrictions do not necessarily affect all account holders in the same way.
Other mechanisms have also enabled capital to exit the system, notably through the repayment of certain commitments to foreign institutions. The banks defended some of these operations by explaining that they must honour their international obligations and maintain their relations with their correspondents.
Justice must therefore avoid shortcuts. Not all foreign currency outflows can be considered as an illicit capital flight. It will be necessary to distinguish between customer transfers, interbank transactions, repayments of international commitments, fresh funds deposited after the crisis and transactions carried out on former deposits.
The seven banks should be just the beginning
The first list sent to the Public Prosecutor ‘ s Office does not end the work of the Bank of Lebanon. Further series of information are expected. The number of officials and institutions concerned could therefore increase as data is processed and communicated to the courts.
This batch progression explains why the names of the seven banks and the 45 to 50 officials should not be presented today as a definitive list of persons liable to prosecution. The hearings constitute a verification phase. The prosecution will then have to decide whether the facts warrant further prosecution, classification or investigation.
The investigation could also go beyond the strict circle of bank leaders. The issue of politically exposed persons, large depositors and beneficiaries related to decision makers had been raised from the outset. Circular 154 had itself placed bank managers and politically exposed persons in a specific category.
If the data provided reveal transfers involving other categories of beneficiaries, the Prosecutor ‘ s Office could therefore have to expand its investigations. At this stage, however, there is nothing to say which people will actually be summoned beyond the first announced series.
Can we recover the transferred funds?
The issue is particularly sensitive to applicants. The opening of the judicial file naturally feeds the hope that capital transferred abroad can return to the Lebanese banking system. But the legal equation is more complex than just automatic restitution.
In order to recover a transfer by judicial means, one must be able to establish the legal basis for requiring it. If the funds came from a legitimate account and the transfer did not violate any applicable provisions, their movement abroad did not retroactively become an offence because the banking system then collapsed.
The situation would be different if the investigation established an offence, misappropriation, laundering, abuse of authority or other criminally reprehensible conduct. Mechanisms of seizure, restitution or international cooperation could then come into play, depending on the facts and jurisdiction in which the assets are located.
That is why the work that begins cannot be reduced to a transfer hunt. Justice must rebuild operations and their conditions of authorization.
A question directly related to the losses of applicants
The investigation comes at a time when Lebanon has still not resolved the fundamental issue of the distribution of losses in the financial system. Since 2019, much of the old foreign currency deposits remain inaccessible under the original contractual terms. The Bank of Lebanon itself recognizes that the restrictions introduced since October 2019 still prevent hundreds of thousands of depositors from freely disposing of their funds.
The question of privileged transfers therefore takes on a dimension that goes beyond those summoned. While some actors were able to protect a significant part of their assets before or during the collapse, capital that left the system was no longer available when losses were crystallized. This does not mean that each dollar transferred constitutes an illegal loss imposed on other depositors. But this justifies determining precisely which transfers have been authorized, to whom and according to which rules.
The file thus joins that of bank restructuring. Before finally determining who will bear the losses — shareholders, banks, Bank of Lebanon, State or depositors — identifying possible preferential transactions becomes a matter of liability as well as accounting.
A second review of foreign currency movements is under way
The case submitted to Judge Maher Cheaïto is only one of the first parts of the work on capital outflows. A second review focuses on currency movements during the critical period of the financial crisis. The objective is to replenish flows with sufficient precision to distinguish ordinary transactions from transfers that could have benefited from special conditions. In particular, this analysis should allow for the reconciliation of dates, amounts, identity of beneficiaries and decisions taken within the institutions concerned.
This step is essential because transfers to abroad cannot be valued solely on the basis of their amount. Their chronology is just as important. A transfer made before the first banking restrictions appeared does not necessarily raise the same questions as an authorized transaction after the banks closed in October 2019, when depositors began to lose the free disposal of their accounts. Investigators will therefore have to determine under what conditions each order was executed and whether the rules applied were identical for bank managers and their clients.
The study period, which begins on 1 July 2019 and runs until 1 December 2023, allows us to cover precisely the months preceding the public collapse of the system. This choice gives the court the opportunity to examine movements made before October 17, 2019, the date of the start of the protest movement, and then those that occurred after the banks introduced informal restrictions on withdrawals and transfers. The timetable can thus become a decisive element of the survey.
Why summer 2019 transfers are crucial
During the summer of 2019, there were already many signs of financial tension. The Bank of Lebanon has been seeking for several years to attract the currencies needed to finance a system based on bank deposits, the needs of the State and the defence of the official parity of the pound. Commercial banks were directly integrated into this mechanism as a significant part of their resources were either placed with the BDL or invested in public debt.
The question raised by the investigation is not, therefore, just how much money came out of Lebanon after the crisis was clearly triggered. It also involves determining whether certain officers, directors, major shareholders or persons related to institutions have transferred capital at the time the deterioration of the financial situation was already known within the sector. However, the presence of a transfer during this period would not be sufficient to demonstrate an infringement. The specific circumstances of the transaction should be established and, where appropriate, the existence of an advantage or information that other applicants did not have.
This distinction is indispensable. Until the late introduction of a legal framework for capital control, Lebanon had not adopted a general law prohibiting bank transfers abroad at the beginning of the crisis. However, banks have begun to apply their own restrictions to customers. It is this coexistence between the initial absence of uniform statutory supervision and the limitations imposed in practice that makes judicial review particularly complex.
The core of the case: privileged transfers
The bankers’ hearings should thus enable the financial prosecutor to understand how transfer decisions were made within institutions. Judges may seek information on who had the authority to authorize a transaction, what internal procedures were applied and whether some beneficiaries obtained transfers, while comparable applications were denied to other clients.
This issue is directly related to the experience of applicants after October 2019. While banks gradually limited dollar withdrawals and prevented much of international transfers, reports of large capital outflows quickly fueled public anger. For several years, the lack of complete banking data and the obstacles related to bank secrecy prevented a comprehensive photograph of these movements.
The investigation conducted by Maher Cheaito changes the nature of the case if the data transmitted by the Bank of Lebanon now allow to work on individualised operations. Judges would no longer only face global estimates or political accusations. They could compare specific movements, identified accounts and specific bank decisions.
Billions of dollars from the beginning of the crisis
The issue of capital coming out of Lebanon had been raised in the first few months of the collapse. In January 2020, the former governor of the Bank of Lebanon, Riad Salamé, mentioned before the media an amount of about $2.3 billion transferred abroad between 17 October and the end of 2019. This figure was for transfers made over a specific period and was not an estimate of all capital that left the country before and after the start of the crisis.
Other estimates, sometimes significantly higher, then circulated in the political and financial debate. They are not all based on the same perimeter and therefore should not be added up or presented as an established legal amount. Some take into account transfers made before October 2019, some take into account subsequent outflows, while some evaluations include different types of financial transactions.
This is precisely one of the interests of the work undertaken by the Public Prosecutor’s Office: gradually replacing estimates with individualised banking data. Final amounts can only be established after consolidation of information from institutions and verification of the nature of operations. At this stage, therefore, the largest figure is not yet an uncertain total, but the number of persons and banks already included in the first set of data handed over to justice: about 45 to 50 administrators and senior officials from seven institutions.
Names of banks become a central issue
The identification of the institutions concerned is now one of the main issues in the dossier. The first judicial information relates to seven banks, but the transmission of data must continue and the scope can be further expanded. Banks whose officials appear on the lists cannot be considered guilty solely because of their presence in the file. Similarly, a leader summoned to provide explanations is not necessarily charged.
However, this legal precaution should not prevent the appointment of institutions when their involvement in a procedure is officially documented. The Lebanese banking sector has long benefited from a strong opacity regarding the beneficiaries of transfers made during the crisis. The gradual removal of certain obstacles related to bank secrecy and the transmission of information to the public prosecutor’s office now allow for a general debate on « banks » to be moved from examining transactions linked to specific individuals and institutions.
This may also lead judges to compare the internal policies of different institutions. Not all banks have necessarily applied the same criteria or allowed the same types of transfers. The investigation should therefore avoid abstract collective responsibility and examine the decisions taken during the period under review by institution.
Bank secrecy has slowed down investigations for a long time
Banking secrecy is one of the historical elements of the Lebanese financial model. Adopted in 1956, it had helped to make the country a regional financial centre capable of attracting capital from the Middle East and its diaspora. After 2019, however, it became a major obstacle to investigations into financial flows and the origin of wealth.
Under pressure from the crisis and the demands of financial reforms, Parliament has gradually changed the banking secrecy regime. The amendments extended access to information for certain authorities, particularly in the context of financial investigations. The practical scope of these changes has been discussed, but they have opened up possibilities that did not previously exist under the same conditions.
For foreign transfers, access to accounts is crucial. It enables the economic beneficiaries of operations to be verified, movements between accounts and, where information is available, their destination to be monitored. It may also permit the search for links between a bank manager and accounts held by relatives or related legal structures.
Families and persons with signing power
Investigations should not necessarily stop at accounts held directly on behalf of directors and officers. The work undertaken by the Financial Prosecutor’s Office also focused on the possibility of examining transactions involving spouses, children, agency directors or persons with signing authority.
This enlargement responds to a classic difficulty of financial investigations. A transfer may be made to a person other than the person who is economically responsible for the transfer. Investigators must therefore reconstitute links between account holders, beneficial owners and those who have ordered or authorized transactions.
The existence of a family or professional relationship is obviously not evidence of irregularity. However, it may justify verification when a financial transaction is likely to be linked to a person already within the scope of the investigation. It is on the basis of these reconciliations that the courts may determine whether mechanisms have been used to circumvent restrictions or conceal the identity of the actual beneficiary.
Policy makers could also be involved
The case could go beyond the banking sector. Since the beginning of the crisis, requests for investigations into transfers abroad also concern politicians, senior officials and persons considered politically exposed. Banking data could be used to verify whether some of these individuals made significant movements during the period under review.
Again, the mere existence of a transfer does not make it possible to conclude an infringement. A political official could legally dispose of an account abroad or make a transfer before the restrictions were applied. The issue would be to determine the origin of the funds, the timing of the transaction and the conditions under which the bank executed it.
A possible extension of the investigation to politicians would nevertheless give another dimension to the case. The Lebanese banking crisis is the result of a prolonged interaction between the State, the Bank of Lebanon and commercial banks. Examining only bank managers without verifying transactions for the benefit of persons with political power would therefore leave an essential part of financial flows outside the scope of investigation.
The question of the return of funds
Maher Cheaito had already placed the recovery of capital at the centre of his action. After his arrival at the head of the financial prosecutor’s office, steps had been taken to ensure that some persons who had transferred funds abroad during the crisis re-possessed in Lebanon equivalent amounts, in the same currency.
This approach raises a different question than that of criminal responsibility. A court proceeding must determine whether an offence has been committed and who can answer for it. The return or repatriation of funds requires, for its part, establishing the legal basis for requiring their return and the conditions under which this measure may be applied.
The subject is particularly sensitive for applicants. If privileged or illicit transfers were established, the question would no longer be simply to punish their perpetrators. It would also be necessary to determine whether the sums could be recovered and reintegrated into the Lebanese financial system, particularly when beneficiaries or assets were in foreign jurisdictions.
International cooperation may become necessary
Some of the capital involved has, by definition, left Lebanese territory. When the funds have been transferred to foreign accounts, Lebanese judges alone do not have all the means to identify, block or obtain their restitution.
Requests for mutual legal assistance may then become necessary. They allow a Lebanese magistrate to request from a foreign authority bank information, documents or, where legal conditions are met, precautionary measures on certain assets.
European proceedings in recent years around Riad Salamé have shown that international judicial cooperation can be used to trace complex financial circuits and identify assets located in several countries. However, there is a distinct logic in the case of transfers by bank managers and each transaction must have its own legal basis.
The ability of the financial prosecutor to document the facts accurately will therefore be decisive. The more detailed the information provided by the Bank of Lebanon, the more the magistrates can make targeted requests to their foreign counterparts if the investigation reveals elements that could justify cooperation.
Banks face their own 2019 decisions
Beyond the amounts, the investigation brings the banking sector back to the question that has poisoned its relations with depositors for almost seven years: on what basis did the banks decide who could transfer its money and who should remain blocked?
After October 2019, institutions gradually imposed withdrawal ceilings and restrictions on international transfers. These measures were implemented without a general capital control law for much of the crisis. Conditions varied according to banks, accounts and periods.
This situation has created a fundamental difference between depositors able to raise their funds and those whose savings have remained immobilized. If the investigation establishes that directors, officers, large shareholders or preferred clients have been granted access to transfers denied to others, the court will have to determine whether this difference in treatment was merely a matter of commercial decisions of the institutions or whether it constituted a breach of their obligations and, in some cases, a criminal offence.
It is on this ground that the hearings announced take on their real importance. Bankers will not only be asked about the accounting existence of a transfer. They may have to explain the decision-making mechanisms that allowed its implementation at the time the banking system began to close to other depositors.
Seven banks today, other lists expected
The first series is handed over to the Public Prosecutor ‘ s Office, covering approximately 45 to 50 administrators and senior officials of seven banks. However, this number does not constitute the definitive scope of the investigation. More data is still needed, which means that new institutions and people could join the file.
It will also be necessary to distinguish between the different judicial stages. To be included in data transmitted to the Public Prosecutor’s Office does not amount to prosecution. Being summoned for a hearing does not mean that a charge will follow. The judge shall examine the documents, hear the persons concerned and determine, for each operation, whether the evidence gathered warrants further action.
This individualized procedure explains why names are now becoming so important. After years of global figures and collective accusations against the banking sector, the case is entering a phase where responsibilities can be linked to concrete decisions. The first hearings should identify who ordered the transfers, who authorized them, who benefited from them and on what criteria they were carried out.
For applicants, a question that has not been answered since 2019
Finally, the scope of the investigation goes beyond those who will be summoned. Since 2019, Lebanese depositors have borne a considerable part of the consequences of bank collapse. The dollar accounts were subject to restrictions, withdrawals were made using successive mechanisms imposing variable losses and the real value of a large part of the deposits remained uncertain.
Meanwhile, the question of capital flows before and during the crisis never received an exhaustive answer. Who transferred money? How much? When? To which destination? With whose permission? And above all, were these operations accessible to all customers under the same conditions?
The work now under way on the Bank of Lebanon data can provide factual answers to these questions. It alone will not solve the banking crisis or automatically restore locked-in savings. But it can establish whether, at the time the system closed to its depositors, some persons with economic or banking power managed to put their capital into shelter under conditions that other clients no longer had access to.
The first hearings to be held before financial attorney general Maher Cheaïto are a new step. Approximately 45-50 directors and senior officials of seven banks are included in the first set of information already provided. Other lists must follow. The next challenge is therefore less whether capital has left Lebanon — this fact has been established for a long time — than precisely identifying the beneficiaries, the amounts and the mechanisms that allowed these transfers between July 2019 and December 2023.